
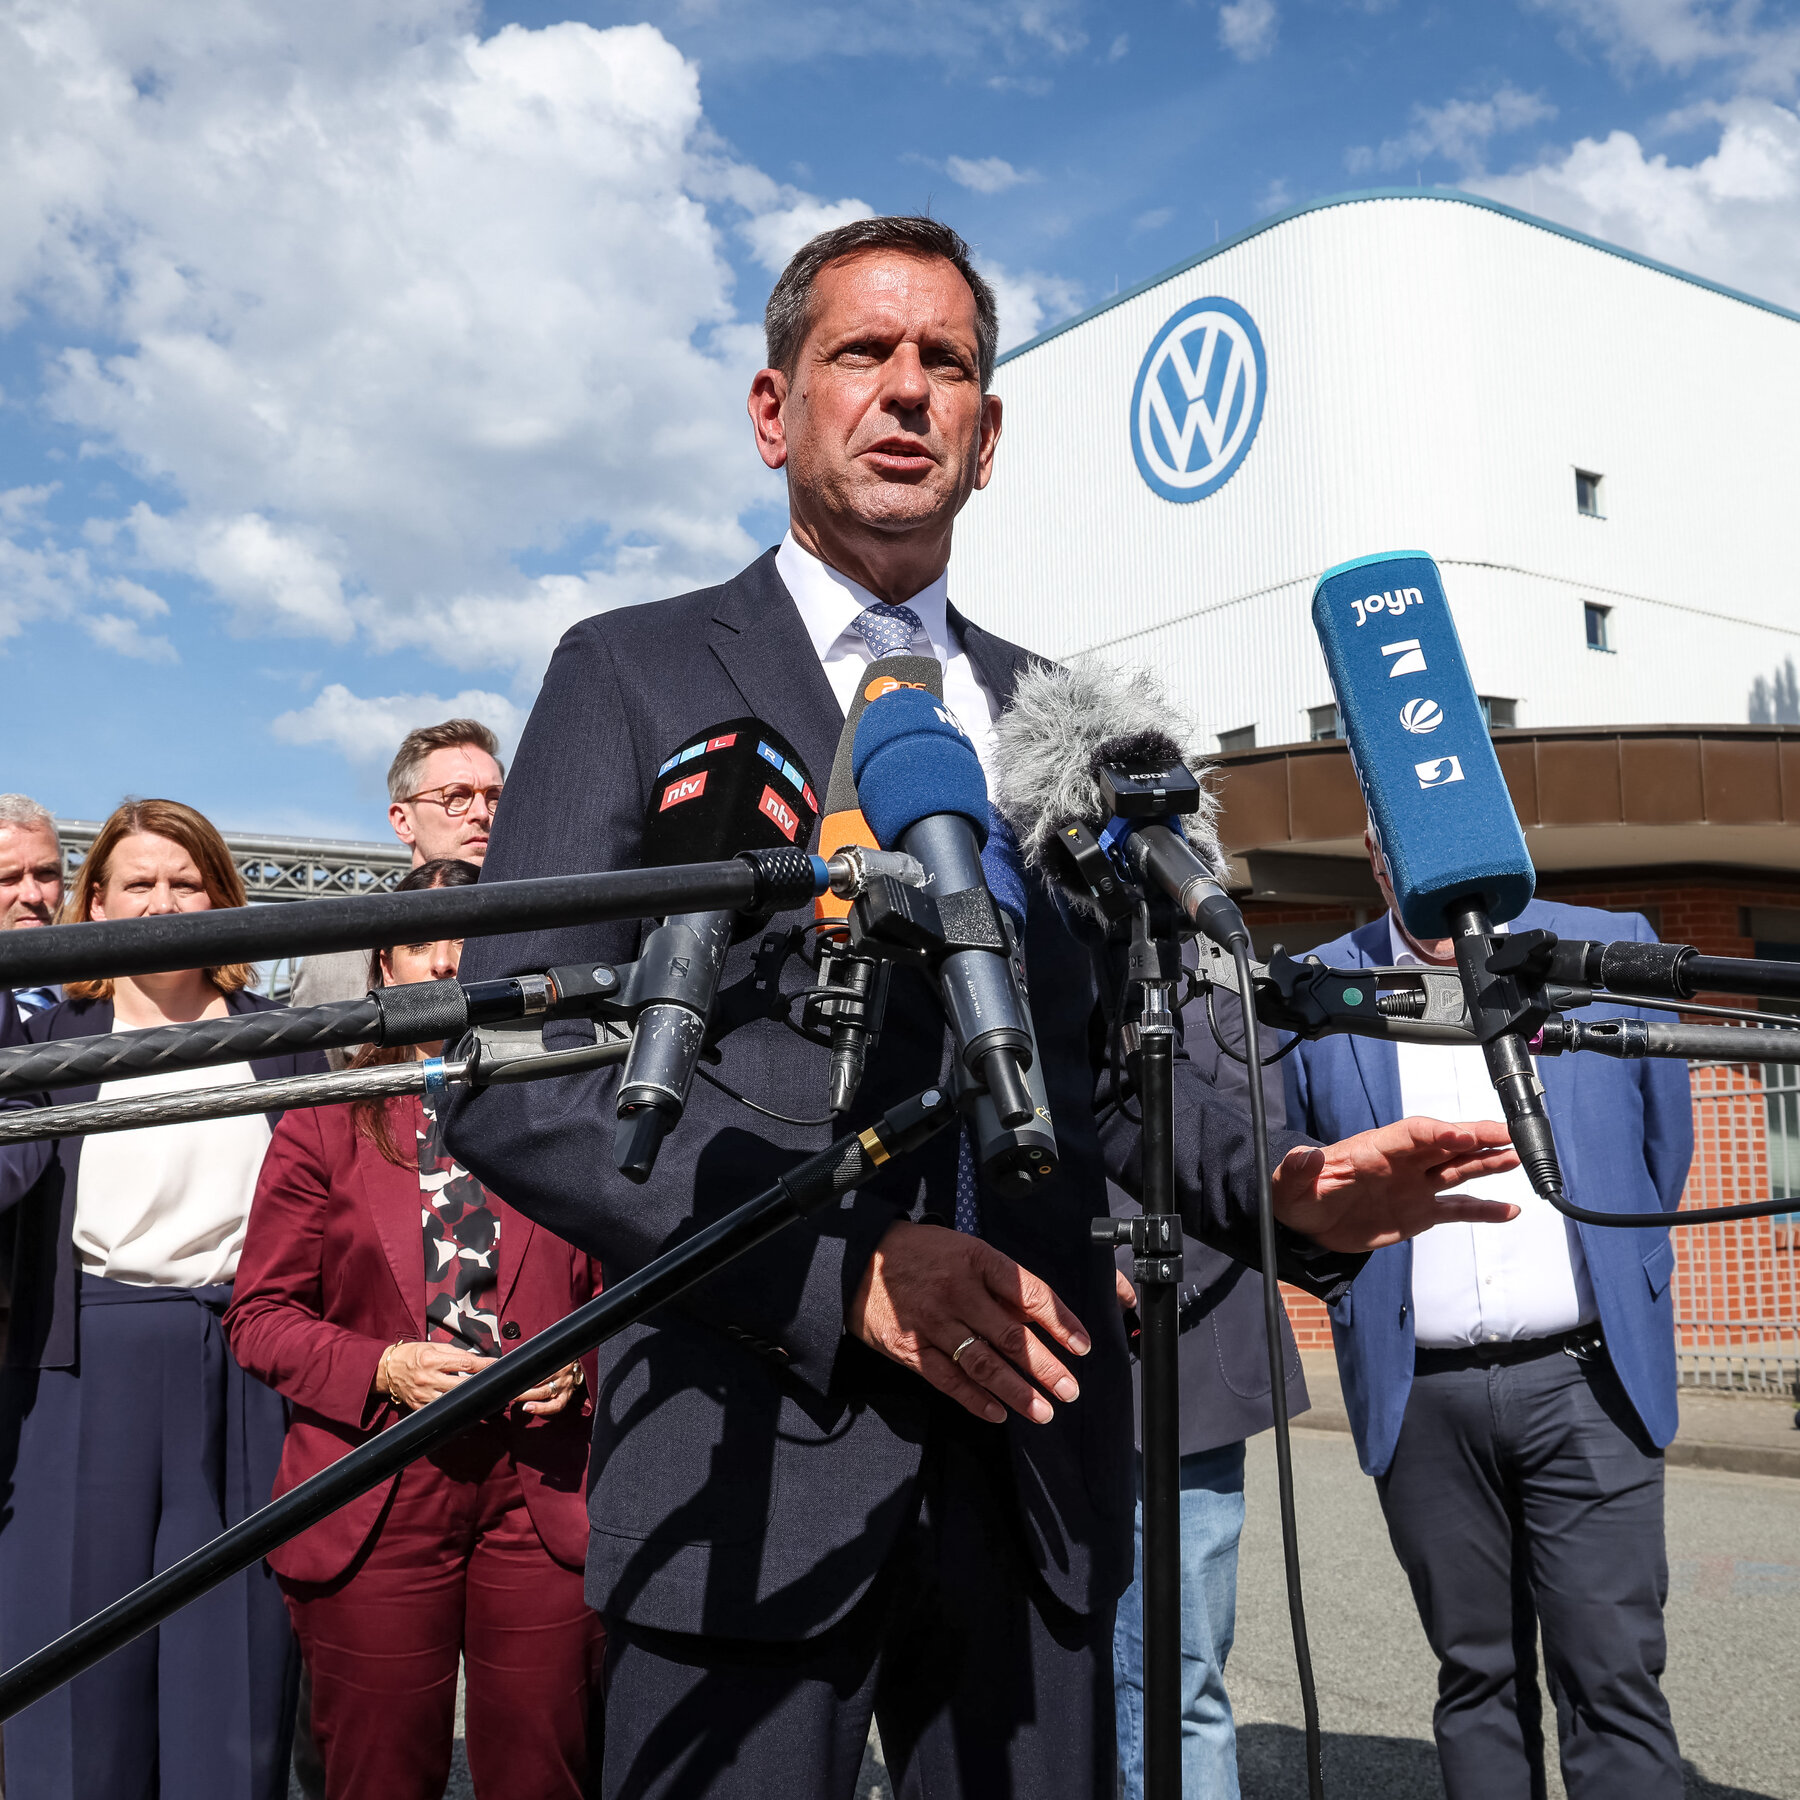
Major European automotive hubs facing severe structural declines are increasingly turning to military manufacturing partnerships to preserve industrial jobs and salvage underutilized infrastructure. As commercial vehicle sales lag and global competitive pressures mount, industrial leaders in Germany are finalizing plans to repurpose struggling facilities for defense equipment. While the initiative delivers immediate local relief, industry analysts caution that retooling civilian plants cannot fully offset widespread automotive contraction.
Strategic Pivot Across Automotive Assembly Lines
The transition represents an unprecedented convergence between continental defense contractors and traditional automakers struggling with the shift toward electrification. Under newly brokered agreements, manufacturing facilities once dedicated to passenger vans and family sedans are being evaluated for tactical vehicle assembly and heavy armor maintenance. Defense officials view these facilities as critical logistical assets capable of rapidly scaling output to meet surging European security procurement requirements.
However, converting precision consumer assembly lines into heavy defense infrastructure presents enormous operational challenges. Automotive manufacturing relies on high-speed automation, standardized components, and lean inventory models that fundamentally contrast with the custom engineering and stringent security standards required for armored vehicle production. Plant managers must completely reconfigure shop floors, upgrade heavy lifting equipment, and secure specialized regulatory certifications before any military hardware rolls out.
Workforce Retraining and Structural Impediments
Labor unions and regional economic development councils have welcomed the defense sector investments as a vital lifeline for endangered manufacturing payrolls. Thousands of assembly technicians facing potential layoffs are slated to enter specialized retraining programs focused on ballistic metallurgy, defense mechanics, and classified electronics. These retraining initiatives aim to bridge the technical gap, ensuring veteran autoworkers retain employment while supporting national defense preparedness programs.
Despite these ambitious programs, defense manufacturing cannot match the massive labor capacity of traditional automotive production lines. Commercial automotive facilities often employ tens of thousands of workers across complex multi-tiered supply chains, whereas specialized defense contracting operates on significantly smaller, batch-oriented labor footprints. Even with robust public procurement funding, defense operations will absorb only a fraction of the workers displaced by broader automotive plant cutbacks.
Security clearance protocols also present unexpected administrative bottlenecks for workforce integration. Every technician, engineer, and plant supervisor working on military hardware must undergo rigorous background checks and government vetting procedures before accessing production zones. Industry observers note that these bureaucratic prerequisites create substantial onboarding delays, preventing instantaneous redeployment of automotive staff across newly designated defense manufacturing sectors.
Escalating Pressure on German Industrial Policy
The industrial shift highlights severe structural headwinds battering Germany and the broader European economic core. High energy prices, elevated regulatory compliance burdens, and aggressive international competition in the electric vehicle sector have severely undermined traditional automakers. As domestic automakers shutter unprofitable lines, regional policymakers are forced to seek alternative economic anchors to prevent cascading deindustrialization across historic industrial heartlands.
Government ministers have defended the dual-use industrial approach as a pragmatic response to shifting geopolitical and economic realities. By coordinating with sovereign defense funds, state planners hope to stabilize core manufacturing regions and preserve sovereign engineering capabilities. Nevertheless, enterprise filings reveal that these state-backed conversions are expensive, demanding significant public subsidies to modernize aged automotive infrastructure for specialized defense applications.
Defense Spending Realities Versus Auto Scale
The scale discrepancy between the commercial vehicle sector and the defense industrial base remains a major economic hurdle. The automotive market generates hundreds of billions of dollars annually through continuous consumer demand and rapid fleet turnover across global markets. In contrast, defense manufacturing is tied directly to government budgetary cycles, political negotiations, and intermittent procurement schedules that lack predictable commercial volume.
Supply chain recalibration poses an additional long-term risk for automotive parts suppliers attempting to pivot toward military contracting. Auto suppliers accustomed to high-volume, low-margin contracts must fundamentally alter their business models to meet defense specifications and export control laws. Many mid-sized tier-two and tier-three suppliers lack the capital reserves and specialized compliance infrastructure needed to survive this complex commercial realignment.
Long-Term Outlook for Continental Manufacturing
Moving forward, the integration of defense production within traditional automotive plants offers a temporary cushion rather than a comprehensive cure for industrial contraction. While defense orders provide steady revenue amid fluctuating consumer demand, they cannot reverse the secular decline in European vehicle production. Industrial leaders emphasize that sustained economic resilience will require broader policy reforms, cheaper energy inputs, and renewed commercial competitiveness.
Ultimately, Europe is witnessing a historic realignment of its industrial capacity as geopolitical priorities reshape legacy manufacturing hubs. The conversion of auto plants into military production facilities illustrates how security imperatives are redefining economic strategy across the continent. Although these defense contracts will preserve essential engineering capabilities and local jobs, the broader automotive sector must still navigate an agonizing, long-term structural transformation.
