The Hayletts' Financial Pivot After Parenthood
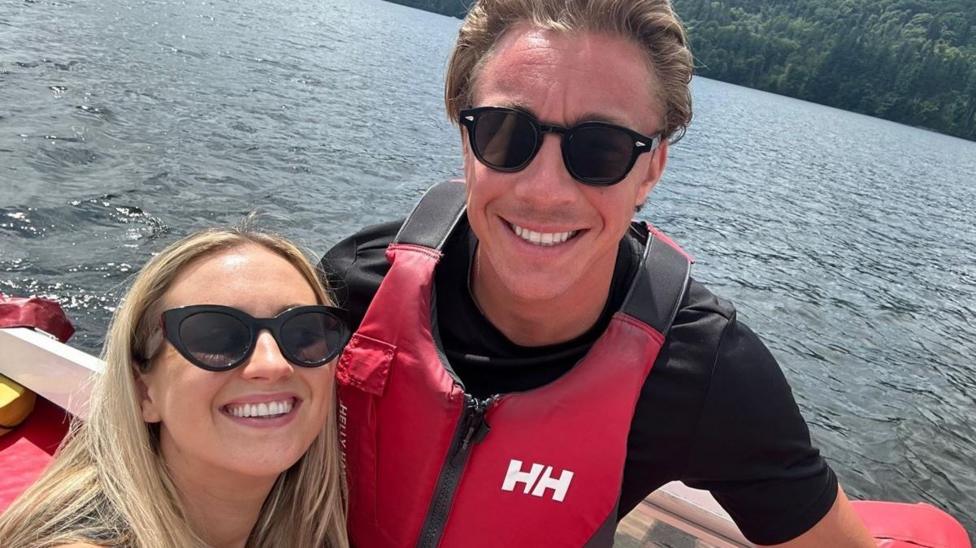
When Molly and Taylor Haylett welcomed their first child, they made a deliberate change to their household finances. Molly asked Taylor to contribute to her pension, a move she says was essential for their long-term security. The decision came after they realized how maternity leave and childcare costs could derail her retirement savings. This personal story highlights a growing trend among couples reassessing their financial strategies when starting a family.
Why Maternity Leave Creates a Pension Gap
Maternity leave often means reduced income or a complete halt to pension contributions, which can create a significant gap in retirement savings. According to industry analysts, women who take time off for childcare can end up with substantially lower pension pots than their male counterparts. This disparity is often called the 'pension gap,' and it can have long-term consequences for financial independence in retirement.
Molly's request was not just about immediate cash flow but about addressing this systemic issue. By having Taylor contribute to her pension during her leave, they ensured that her retirement savings continued to grow. This proactive approach helped mitigate the financial penalty that often accompanies motherhood, a strategy that financial advisors increasingly recommend to young families.
The Mechanics of Spousal Pension Contributions
Spousal pension contributions allow one partner to pay into the other's pension plan, which can be tax-efficient and help maintain contribution levels during career breaks. In many jurisdictions, these contributions qualify for tax relief, making them a smart financial move for couples. The Hayletts decided to redirect a portion of Taylor's income into Molly's pension, effectively treating her unpaid care work as a shared financial responsibility.
Financial experts note that such arrangements require careful budgeting and clear communication. Molly and Taylor had to adjust their monthly spending to accommodate the extra pension payments. They also sought advice from a financial planner to ensure they were maximizing their tax benefits and staying within contribution limits. This meticulous planning turned a potential financial setback into an opportunity for growth.
The Broader Impact on Family Finances
The decision to split pension contributions is part of a larger shift in how modern families manage money. Many couples now view their finances as a joint venture, where both partners' long-term security is prioritized equally. This approach can lead to better financial outcomes for the entire family, as it encourages open discussions about money and future goals.
For the Hayletts, this change also meant reevaluating their budgeting priorities. They cut back on non-essential expenses and redirected those funds into savings and retirement accounts. This disciplined approach helped them maintain their lifestyle while building a more secure financial future. It also set a positive example for their child, demonstrating the importance of planning ahead.
Expert Advice for Couples Considering Similar Moves
Financial advisors suggest that couples discuss pension contributions as part of their overall family financial plan. They recommend reviewing both partners' pension schemes to identify any gaps and exploring options like spousal contributions or salary sacrifice arrangements. These strategies can be particularly beneficial when one partner takes time off work for caregiving responsibilities.
Advisors also emphasize the importance of seeking professional guidance to navigate the complex rules surrounding pension contributions. In some cases, there are limits on how much can be contributed tax-free, and these rules vary by country. By working with a qualified planner, couples can ensure they are making the most of their contributions while avoiding costly mistakes.
The Future Outlook for Family Retirement Planning
As more families adopt this collaborative approach to finances, the pension gap could narrow over time. However, experts warn that systemic changes, such as better parental leave policies and automatic enrollment for all workers, are also needed. The Hayletts' story is a reminder that individual actions can make a difference, but broader societal support is crucial for long-term change.
Molly and Taylor's decision to split pension contributions is not just a personal finance tip; it's a model for other couples to consider. By prioritizing both partners' retirement security, they have taken a significant step toward financial equality within their marriage. Their experience offers valuable lessons for any family navigating the financial challenges of parenthood.
In conclusion, the Hayletts' story underscores the importance of proactive financial planning when starting a family. By asking her husband to contribute to her pension, Molly ensured that her career break did not derail her long-term savings. This simple yet powerful move can serve as inspiration for other couples facing similar decisions, highlighting the benefits of open communication and shared financial goals.
