Federal Initiative Quietly Creates Investment Accounts for Millions of Minors
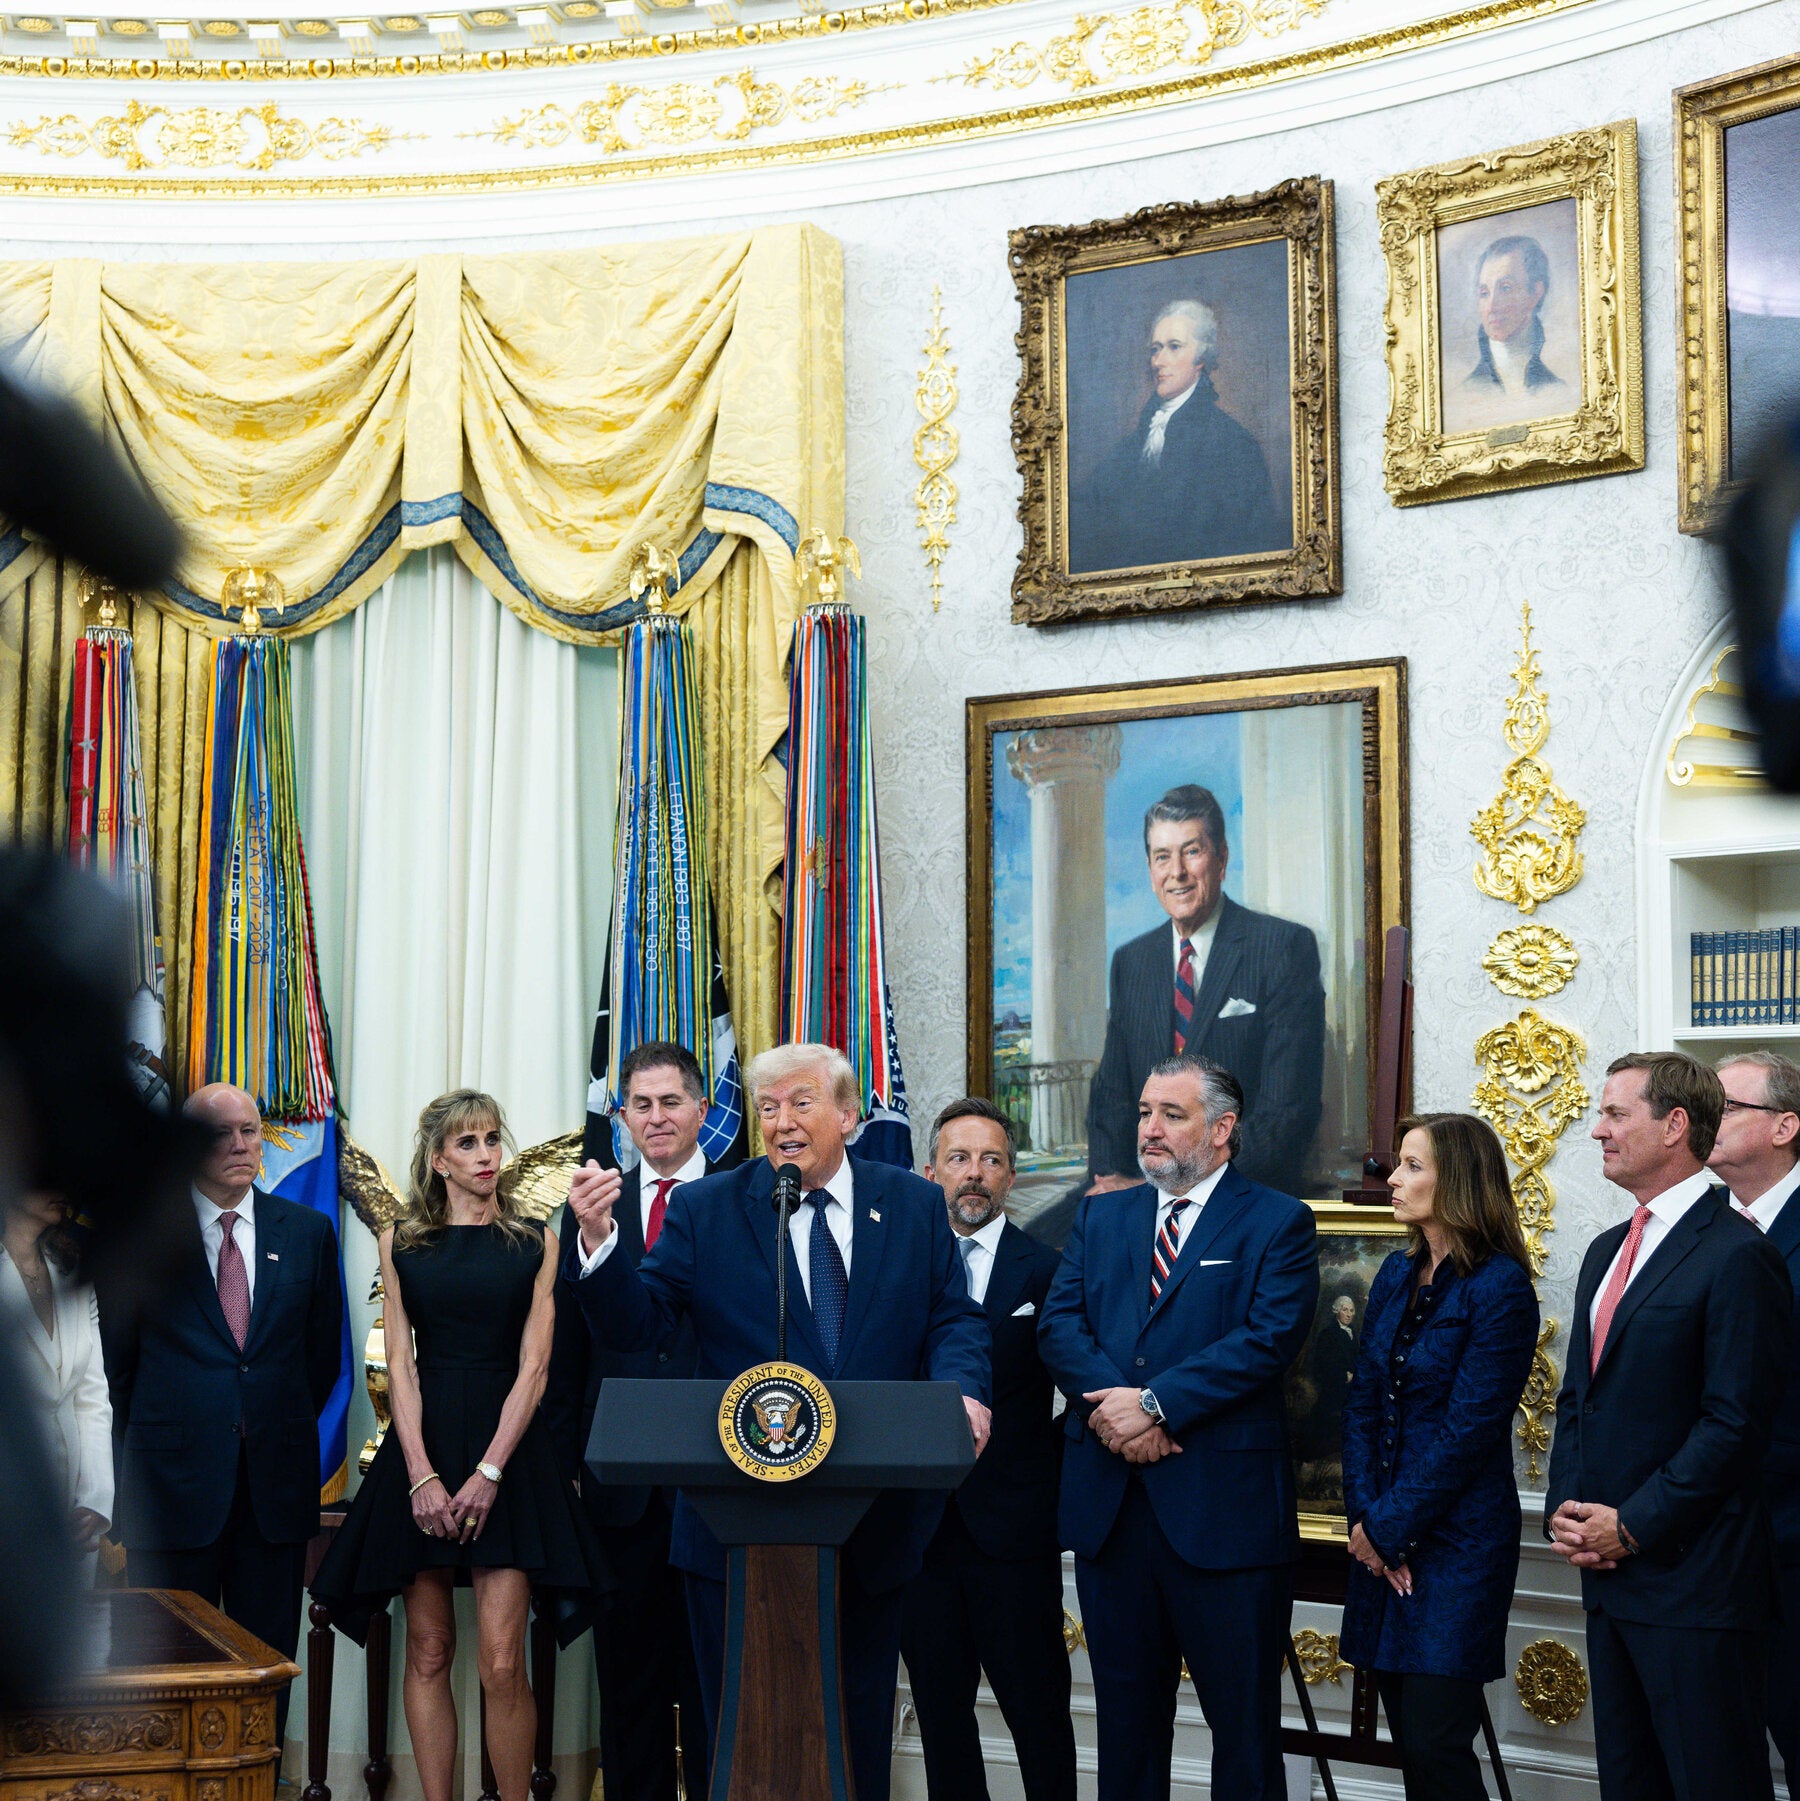
The Trump administration has auto-enrolled more than 60 million American children into newly created 530A savings accounts, a sweeping federal initiative that took effect this week. Parents who have not previously established such accounts for their dependents will find one already exists in their child's name. The program, authorized under recent federal legislation, aims to establish a baseline of personal savings for every minor citizen.
This unprecedented federal action bypasses traditional parental consent, automatically opening accounts for children across all 50 states. The initiative represents one of the largest single financial enrollment efforts in US history. Officials at the Department of the Treasury confirmed that the rollout began Monday, with notifications scheduled to reach households throughout the coming weeks. The program targets children from birth through age 17.
Understanding the 530A Account Structure and Funding Mechanics
A 530A account functions as a tax-advantaged savings vehicle specifically designed for minors. Unlike traditional custodial accounts, these federal accounts come with unique contribution limits and withdrawal restrictions. The accounts are seeded with an initial federal deposit of $500, funded through the general treasury. Annual contributions from family members are permitted up to $2,000 per child, subject to income phase-outs.
Account funds remain accessible for qualified educational expenses, first-home purchases, or rollover into retirement vehicles upon the child reaching adulthood. However, non-qualified withdrawals trigger income tax plus a 10% penalty. Financial advisors note that the automatic nature of enrollment creates immediate tax implications. Parents should review their 2025 filing status carefully, as the initial federal deposit may require reporting.
How Parents Can Locate and Manage Their Child's New Account
The Treasury Department has established a dedicated online portal for parents to access their child's 530A account information. Verification requires the child's Social Security number, parent's identification, and proof of guardianship documents. The portal displays current balance, contribution history, and available investment options. Parents can also designate beneficiaries or adjust the default investment allocation, which currently mirrors a conservative bond-heavy portfolio.
Households without reliable internet access can contact the Federal Savings Administration's toll-free line, operational Monday through Friday. Representatives assist with account verification, address updates, and opt-out requests. The agency has also partnered with local social security offices to provide in-person assistance. Early reports indicate high call volumes, with average wait times exceeding 30 minutes during peak hours.
Opt-Out Provisions and Potential Penalties for Families
The auto-enrollment includes a 90-day opt-out window, during which parents can close the account without penalty. After this period, the account becomes permanent, and the initial federal deposit becomes subject to recapture. Closing an account after the opt-out window requires repaying the $500 seed amount, plus accrued interest. This provision has drawn criticism from privacy advocates concerned about federal overreach.
Families choosing to maintain the account face no direct costs or maintenance fees. However, the federal deposit may affect eligibility for need-based programs such as Supplemental Security Income or Medicaid. Financial planners recommend consulting with a tax professional before making any decisions. The opt-out process itself requires notarized documentation, adding a layer of complexity for households in rural or underserved areas.
Economic Impact and Long-Term Savings Projections
Economists project that the 530A program could inject up to $30 billion into financial markets over the next decade. The accounts are designed to compound through conservative investment strategies, with projected average annual returns of 4-6%. If maintained until age 18, the initial $500 deposit could grow to approximately $1,000, assuming consistent contributions from family members.
The broader economic implications extend beyond individual savings. Industry analysts suggest that the program could stimulate the retail investment sector by introducing a new generation to financial markets. Financial institutions are developing specialized products tailored to 530A account holders, including low-cost index funds and target-date portfolios. Critics question whether the administrative costs outweigh the benefits, particularly for lower-income families.
State-Level Implementation and Coordination Challenges
State treasurers have reported varied levels of preparedness for the federal rollout. Some states, including California and New York, have established supplementary programs that align with the federal initiative. Others are still developing infrastructure to handle inquiries and data sharing. The Treasury Department has provided grants to assist states with implementation, but several have cited technology gaps and staffing shortages.
The coordination between federal and state systems has created some confusion regarding tax treatment. While the accounts are federally tax-advantaged, state tax codes vary significantly. At least twelve states have not yet clarified their position on 530A accounts, leaving parents uncertain about state-level tax liabilities. The National Governors Association has requested additional guidance from the Treasury Department.
Next Steps for Families and Future Policy Considerations
Parents are advised to review their notification letters carefully and verify that all personal information is accurate. The Treasury Department has established a 60-day window for correcting data errors, after which changes require formal amendment requests. Families should also consider their long-term financial goals when deciding whether to maintain, contribute to, or opt out of the accounts.
The auto-enrollment program represents a significant shift in federal savings policy, with potential implications for future generations. Legislative observers note that the program could be expanded or modified depending on the 2026 budget cycle. For now, families across the nation are navigating this new financial landscape, balancing immediate concerns with long-term planning for their children's economic futures.
