
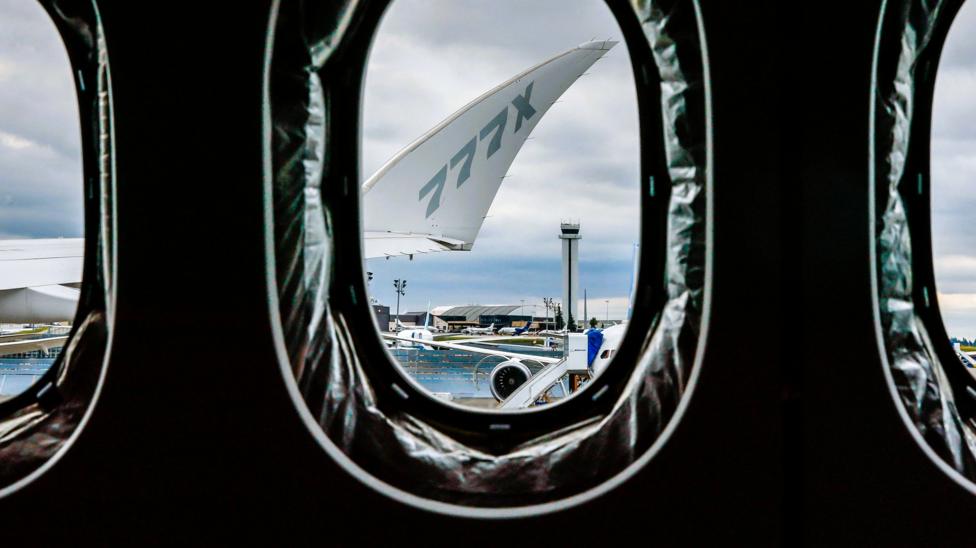
Global aerospace manufacturers are confronting critical production bottlenecks as the extreme engineering requirements for commercial aircraft windows limit output to a handful of certified global suppliers. Industry analysts confirm that modern cabin designs, higher cruising altitudes, and stringent safety standards have created unprecedented technical hurdles, leaving major airframe assemblers vulnerable to severe supply chain delays during a period of historic fleet expansion.
Uncompromising Physics and Cabin Pressure Challenges
Commercial aircraft windows must endure extraordinary physical stresses while maintaining optical clarity and structural resilience. At typical cruising altitudes exceeding thirty-five thousand feet, external atmospheric pressure drops precipitously while cabin interiors remain pressurized to simulate safe breathing conditions. This differential forces thousands of pounds of continuous outward force against every square foot of the passenger fuselage.
Simultaneously, exterior temperatures regularly plunge below minus sixty degrees Fahrenheit while interior cabins remain heated for passenger comfort. These extreme thermal gradients induce severe mechanical strain on transparent polymers. Engineers must ensure materials expand and contract predictably without delaminating, cracking, or losing crucial optical properties over thousands of flight cycles spanning several decades.
To withstand these punishing conditions, commercial passenger windows utilize multi-layered stretched acrylic panels rather than traditional structural glass. The outer and middle panes bear the cabin pressure loads, separated by an engineered air gap that prevents condensation. A minute bleed hole balances pressure between the layers, preventing catastrophic structural failure if an outer surface suffers damage.
The Specialized Science of Flight Deck Windshields
While passenger cabin windows demand rigorous engineering, cockpit windshield assemblies require an entirely different level of chemical and material sophistication. Cockpit transparencies must withstand direct bird impacts at speeds exceeding three hundred knots while sustaining internal pressurization. Regulatory authorities mandate that flight crews retain forward visibility even after severe physical collisions during takeoff and landing phases.
Cockpit units consist of complex laminates bonding chemically strengthened glass, urethane interlayers, and high-performance polycarbonates. Microscopic electrical wiring or transparent conductive coatings are embedded directly within the glass matrix to provide continuous anti-icing and anti-fogging capabilities. A single commercial airliner cockpit windshield can weigh over one hundred pounds and require months of precision fabrication.
Developing these optical assemblies involves proprietary chemical formulas and cleanroom autoclave curing processes that few companies worldwide have successfully mastered. Slight imperfections in temperature control during lamination can cause microscopic optical distortion or structural weaknesses, forcing manufacturers to scrap entire production batches under uncompromising quality assurance protocols.
Oligopolistic Supply Chains and Industrial Barriers
The capital investment and technical expertise necessary to certify aerospace transparencies have created an intense market concentration. Only a select group of specialized industrial firms hold the regulatory certifications required by civil aviation authorities. This concentrated industrial base leaves aircraft assembly lines extraordinarily vulnerable to minor disruptions at individual component manufacturing facilities.
New market entrants face immense regulatory barriers and multi-year testing regimes before delivering a single flight-certified transparency. Standard verification processes require hundreds of physical impact tests, environmental degradation trials, and exhaustive stress tests. As a consequence, airframe manufacturers cannot easily substitute alternative suppliers when primary transparency vendors encounter production bottlenecks or raw material shortages.
Compounding the challenge is the aerospace sector's broader shift toward next-generation widebody aircraft featuring larger passenger windows. Larger transparent apertures significantly increase passenger cabin ambiance but dramatically reduce structural fuselage margins. Aerospace engineers must compensate with advanced composite framing materials, requiring even tighter manufacturing tolerances from window suppliers.
Regulatory Scrutiny and Future Industry Outlook
Civil aviation regulators have intensified oversight of secondary aircraft components following several high-profile pressurization incidents across the commercial fleet. Aviation safety inspectors now require comprehensive lifecycle tracking for every installed transparency panel, mandating scheduled replacements based on flight hours and environmental exposure rather than visual wear alone.
To address growing production constraints, research institutions and aerospace material specialists are investing heavily in advanced ceramics and self-healing optical polymers. Experimental transparent ceramic materials offer superior scratch resistance and thermal stability compared to traditional stretched acrylics, potentially reducing maintenance intervals and extending overall operational service life for commercial transport fleets.
However, commercializing these advanced materials at scale remains years away from broad industrial adoption. For the immediate future, global aviation growth remains tightly tethered to the specialized manufacturing lines that produce these indispensable transparent barriers, underscoring how foundational materials science governs the expansion of modern air travel.
