Martin Lewis Questions Premium Bonds Appeal
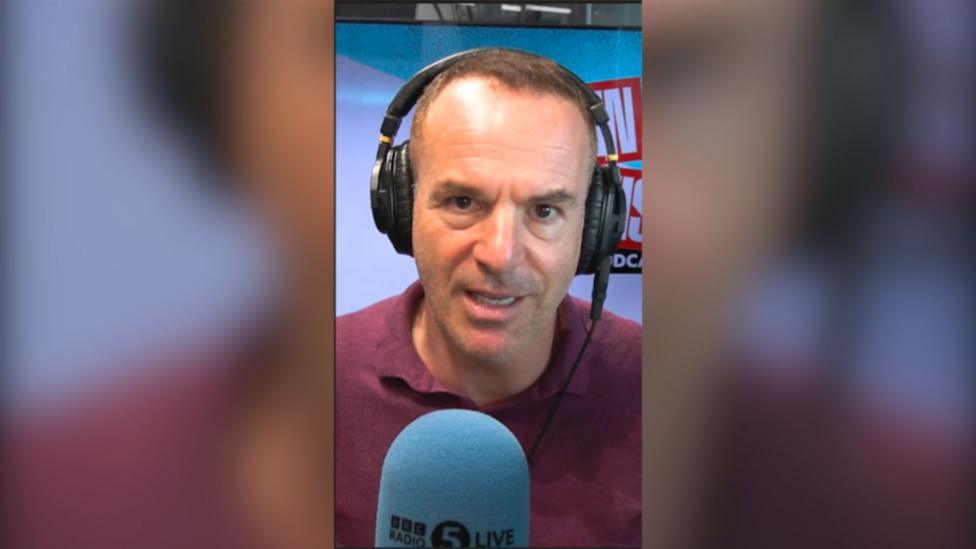
Martin Lewis, the UK's foremost consumer finance expert, has sparked fresh debate over Premium Bonds, the nation's most popular savings vehicle. In his latest analysis, Lewis argues that while these bonds attract millions of savers, they are not universally beneficial. His remarks come as interest rates fluctuate and alternative savings products offer increasingly competitive returns.
Premium Bonds, issued by National Savings and Investments (NS&I), have long been a staple of British saving culture. Instead of earning traditional interest, bondholders enter monthly prize draws with tax-free payouts ranging from £25 to £1 million. With over 22 million people holding bonds, they represent billions in household savings, yet Lewis suggests many could be better off elsewhere.
Who Benefits Most From Premium Bonds
Lewis identifies higher-rate taxpayers as the primary beneficiaries of Premium Bonds. Because prizes are completely tax-free, those paying 40% or 45% tax on savings interest gain a significant advantage. For basic-rate taxpayers, the benefit is less pronounced, especially when comparing against high-interest easy-access accounts currently offering around 5%.
The 'prize rate' for Premium Bonds currently stands at 4.65%, but this is not a guaranteed return. Lewis emphasizes that the median winner receives less than the advertised rate, as the distribution is skewed by large jackpots. For savers with smaller amounts, the actual expected return can be substantially lower, making conventional savings accounts more attractive.
Why Premium Bonds May Disappoint Some Savers
Lewis warns that individuals with modest savings pots, particularly those with under £10,000, often see returns below the headline rate. The odds of winning any prize are 21,000 to 1 per bond per month, meaning smaller holdings may go months without a win. This unpredictability can frustrate savers seeking steady, reliable growth.
Moreover, the effective interest rate for those in the lowest prize tiers is minimal. NS&I data reveals that most prizes are £25 or £50, and the majority of bondholders receive nothing in any given month. Lewis advises that anyone relying on savings for short-term goals should prioritize guaranteed returns over lottery-style chances.
Alternatives to Premium Bonds for Savers
For basic-rate taxpayers and those with emergency funds, Lewis recommends comparing easy-access savings accounts and fixed-rate bonds. Many banks now offer interest rates above 5%, with some accounts providing guaranteed returns that outpace the median Premium Bonds yield. These products also offer instant access and no reliance on luck.
Cash ISAs present another compelling alternative, especially for higher-rate taxpayers who have already used their personal savings allowance. With tax-free interest and similar rates to standard accounts, ISAs provide a predictable way to grow savings. Lewis notes that premium bonds can still complement an ISA, but they should not be the sole savings strategy.
The Role of Premium Bonds in a Balanced Portfolio
Despite his criticisms, Lewis acknowledges that Premium Bonds serve a unique psychological purpose. The chance of winning a life-changing £1 million prize can motivate people to save who might otherwise spend. For those with substantial savings above the FSCS protection limit, bonds offer a safe haven since NS&I is backed by the Treasury.
Financial advisers often recommend holding Premium Bonds as part of a diversified savings portfolio, particularly for higher earners who have maxed out their ISA allowances. The bonds also offer easy access to funds without penalty, making them a flexible option for short-term cash reserves. However, Lewis stresses that they should not replace higher-yielding accounts for core savings.
Future Outlook for Premium Bonds
As the Bank of England adjusts interest rates, the appeal of Premium Bonds will likely evolve. NS&I periodically reviews the prize rate, and recent increases have kept bonds competitive. Yet, with savings rates expected to remain elevated, the gap between guaranteed returns and prize-based yields may widen, prompting more savers to reconsider their options.
Industry analysts suggest that NS&I may need to enhance the prize fund or introduce more smaller prizes to retain investors. The government's funding targets also influence bond rates, as NS&I balances consumer appeal with fiscal objectives. Savers should monitor announcements and regularly reassess their savings strategy to ensure optimal returns.
Expert Advice for Savers
Lewis concludes that Premium Bonds are not inherently bad, but they are not for everyone. He advises savers to calculate their effective return based on their tax bracket and savings amount. For most basic-rate taxpayers, especially those with smaller balances, a straightforward savings account will deliver better results.
For higher-rate taxpayers, bonds remain a valuable tool, but they should be used judiciously alongside other tax-efficient products. Ultimately, the decision hinges on individual circumstances, risk tolerance, and financial goals. By weighing the pros and cons, savers can make informed choices that align with their long-term interests.
Key Takeaways From Martin Lewis's Analysis
Martin Lewis's latest guidance reinforces the importance of personalized financial planning. Premium Bonds offer excitement and tax-free prizes, but they are not a one-size-fits-all solution. Savers must assess their own situation, comparing rates and benefits across all available options to maximize their money's potential.
As the savings landscape continues to shift, staying informed is crucial. Whether you choose Premium Bonds, ISAs, or traditional accounts, the key is to make your savings work harder for you. With expert insights and careful consideration, every saver can find the right balance between security, growth, and the thrill of a potential win.
